| We all know about credit scores, but do you really understand them?
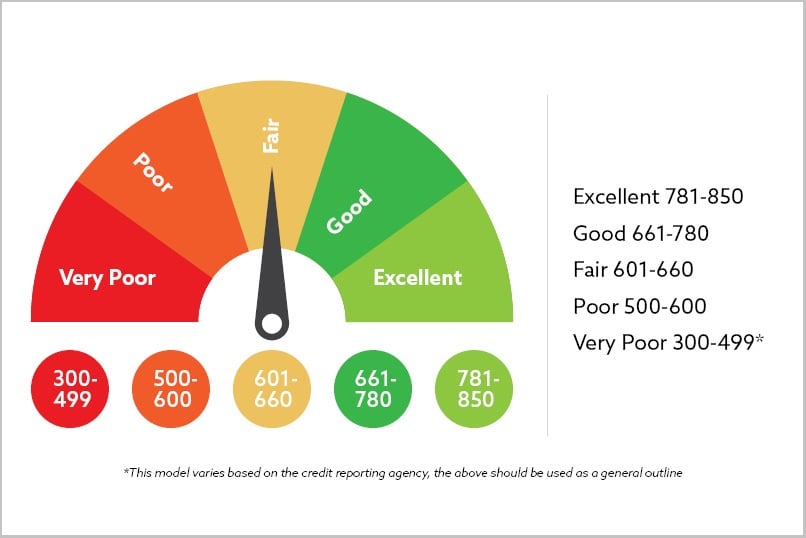
What is your credit score? It is a 3-digit number that lenders use to determine how “likely you are to repay your debt responsibly.” |
 |
| Why is it important?
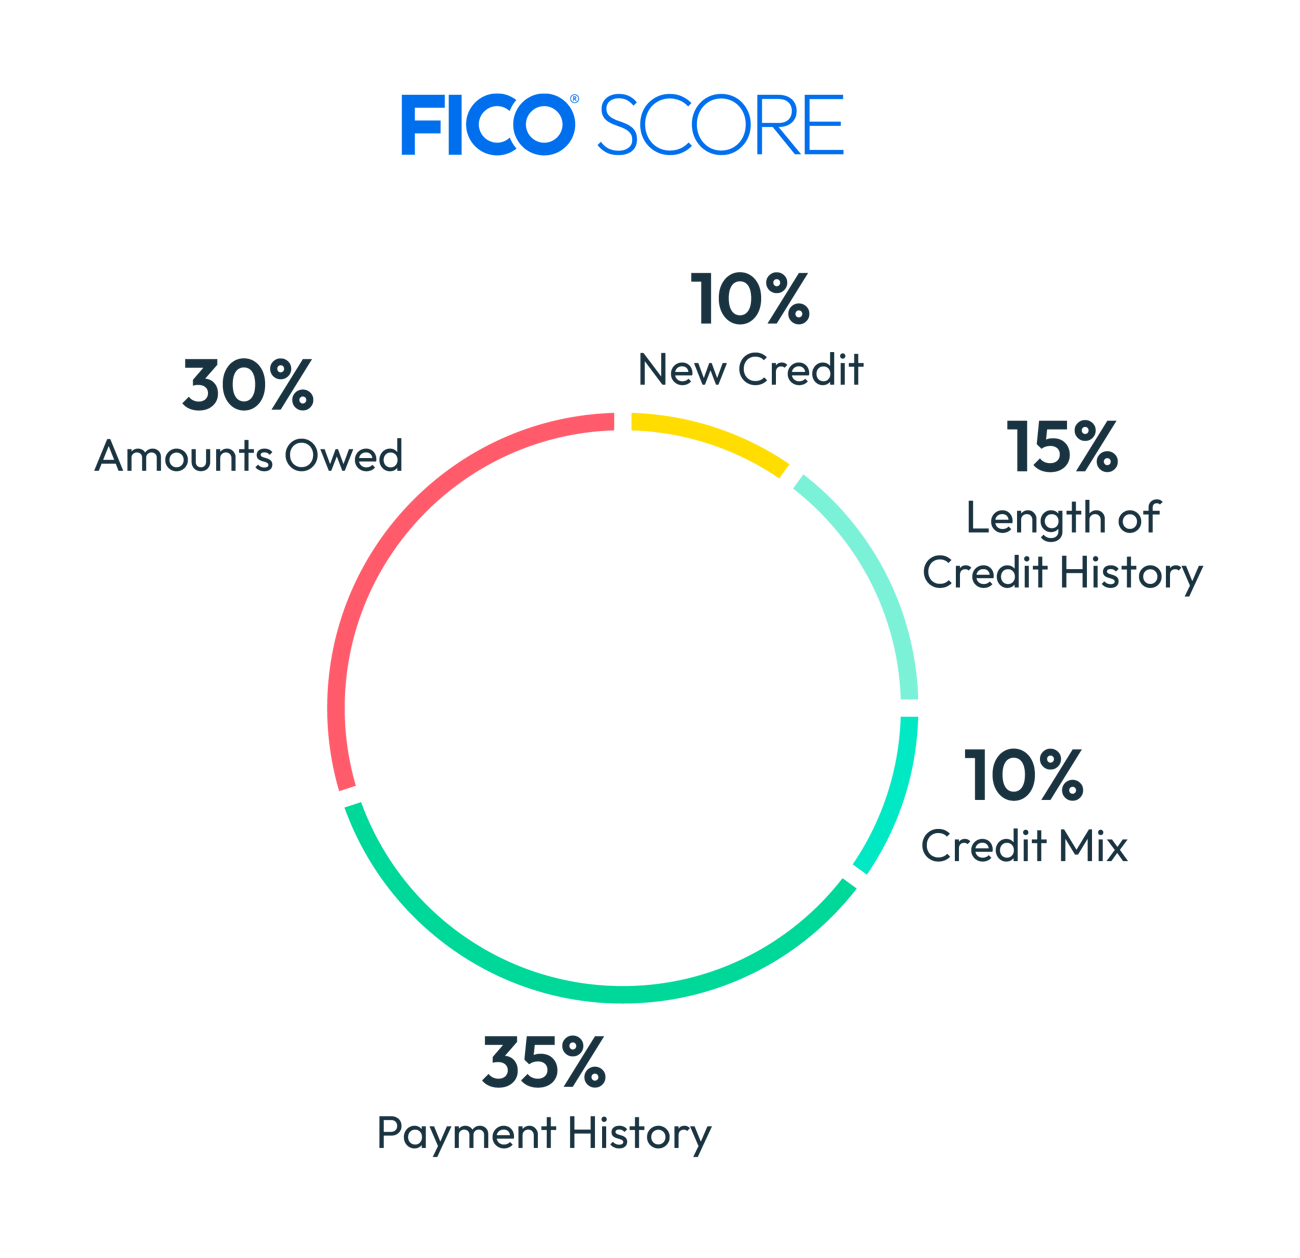
The higher the score, the better rates you will receive on loans for auto, home, credit cards, etc. The lower the score, the more expensive a loan will be. Or you may be at risk of being denied altogether. Did you know your credit score can impact your homeowner and auto insurance rates? Yep, so whether you like it or not, it’s worth paying attention to😕. How do you know your credit score? There are a variety of free resources that will allow you to monitor your credit health. I use CreditWise from Capital One. Another good option is Credit Karma. Just a heads-up: they will have ads for a variety of credit cards and loans. Don’t fall for it. Stay the course, get your score, and get out😉. What to do about it? I wrote an entire blog post with tips on raising your credit score. You can check it out here and there are probably some tips that you hadn’t considered. It’s important to know how the score is calculated. Your credit score is based on based on the following factors: -Payment history: Are you making all of your payments on time? -Amounts owed: Should be less than 30% of your available credit. -New credit: You don’t want to apply for too many new credit accounts. -Length of credit history: The longer your history, the better. -Credit mix: A healthy revolving, installment, and mortgage mix. |
 |
| It’s essential to be proactive with your credit score. When you apply for a mortgage, it is not the best time to realize your score is much lower than expected.
If you’re above a 750, you’re in good shape, and I wouldn’t spend any energy trying to improve it. If you’re below a 750, check out my blog post with tips to improve it. It does take some time, so get started ASAP. |


Site Map
Contact Us
Follow Us
© 2024 • Your Money Project • Privacy Policy • Terms & Conditions • Web Design by JEMSU